VYNN researchNYSE: VRun of 18 Oct 2026
Visa
fair value
On 18 Oct 2026, VYNN’s model valued Visa at $390.24 a share, 3.1% below the $402.61 price. A Hold, published with low confidence.
A dated research record. It does not update, and it is not investment advice.
- Price at the run
- $402.61
- VYNN fair value, 3.1% below the price
- $390.24
- Analysts' mean target, 37 analysts
- $422.77
- Rating, low confidence
- Hold
Price, model and analysts on one scale.
The two methods give $343.80 and $436.68. Their midpoint is the fair value. The price at the run sits between them.
52-week range$293.89 to $404.74
VYNN’s two methods$343.80 to $436.68
37 analysts’ targets$330.00 to $475.00
In VYNN’s rules a Hold is a fair value within 15% of the price, either way; Visa’s is 3.1% below. Confidence is low because both methods rest on one cash-flow forecast, and no independent peer-multiple method was available in this run.
What $402.61 asks of Visa.
A price is a forecast. This is the growth the market was paying for at the run.
At this price, revenue would have to grow about 9% a year for 10 years at the modeled margins; on the same measure, the model's analyst-based forecasts come to about 8% a year.
Read the other way: to justify the price, the business needs terminal free cash flow of $59.10B. The model has $46.75B, so the market is asking for 26.4% more than the model expects.
Two methods, one forecast.
Both discount the same ten years of free cash flow. They differ in how they value what comes after.
Perpetual growth
$343.80 a share
After year ten, cash flow grows 2.5% a year for good.
- Present value of free cash flows
- $237.12B
- Terminal value
- $418.23B
- Enterprise value
- $655.35B
- Equity value
- $645.43B
Exit multiple
$436.68 a share
In year ten, the business is valued at 21.5 times EBITDA, against 24.1 today, held to what a sustainable growth rate justifies.
- Exit multiple (EV/EBITDA)
- 21.5x
- Terminal enterprise value
- $1,253.92B
- Enterprise value
- $829.72B
- Equity value
- $819.81B
Fair value, the midpoint of the two$390.24
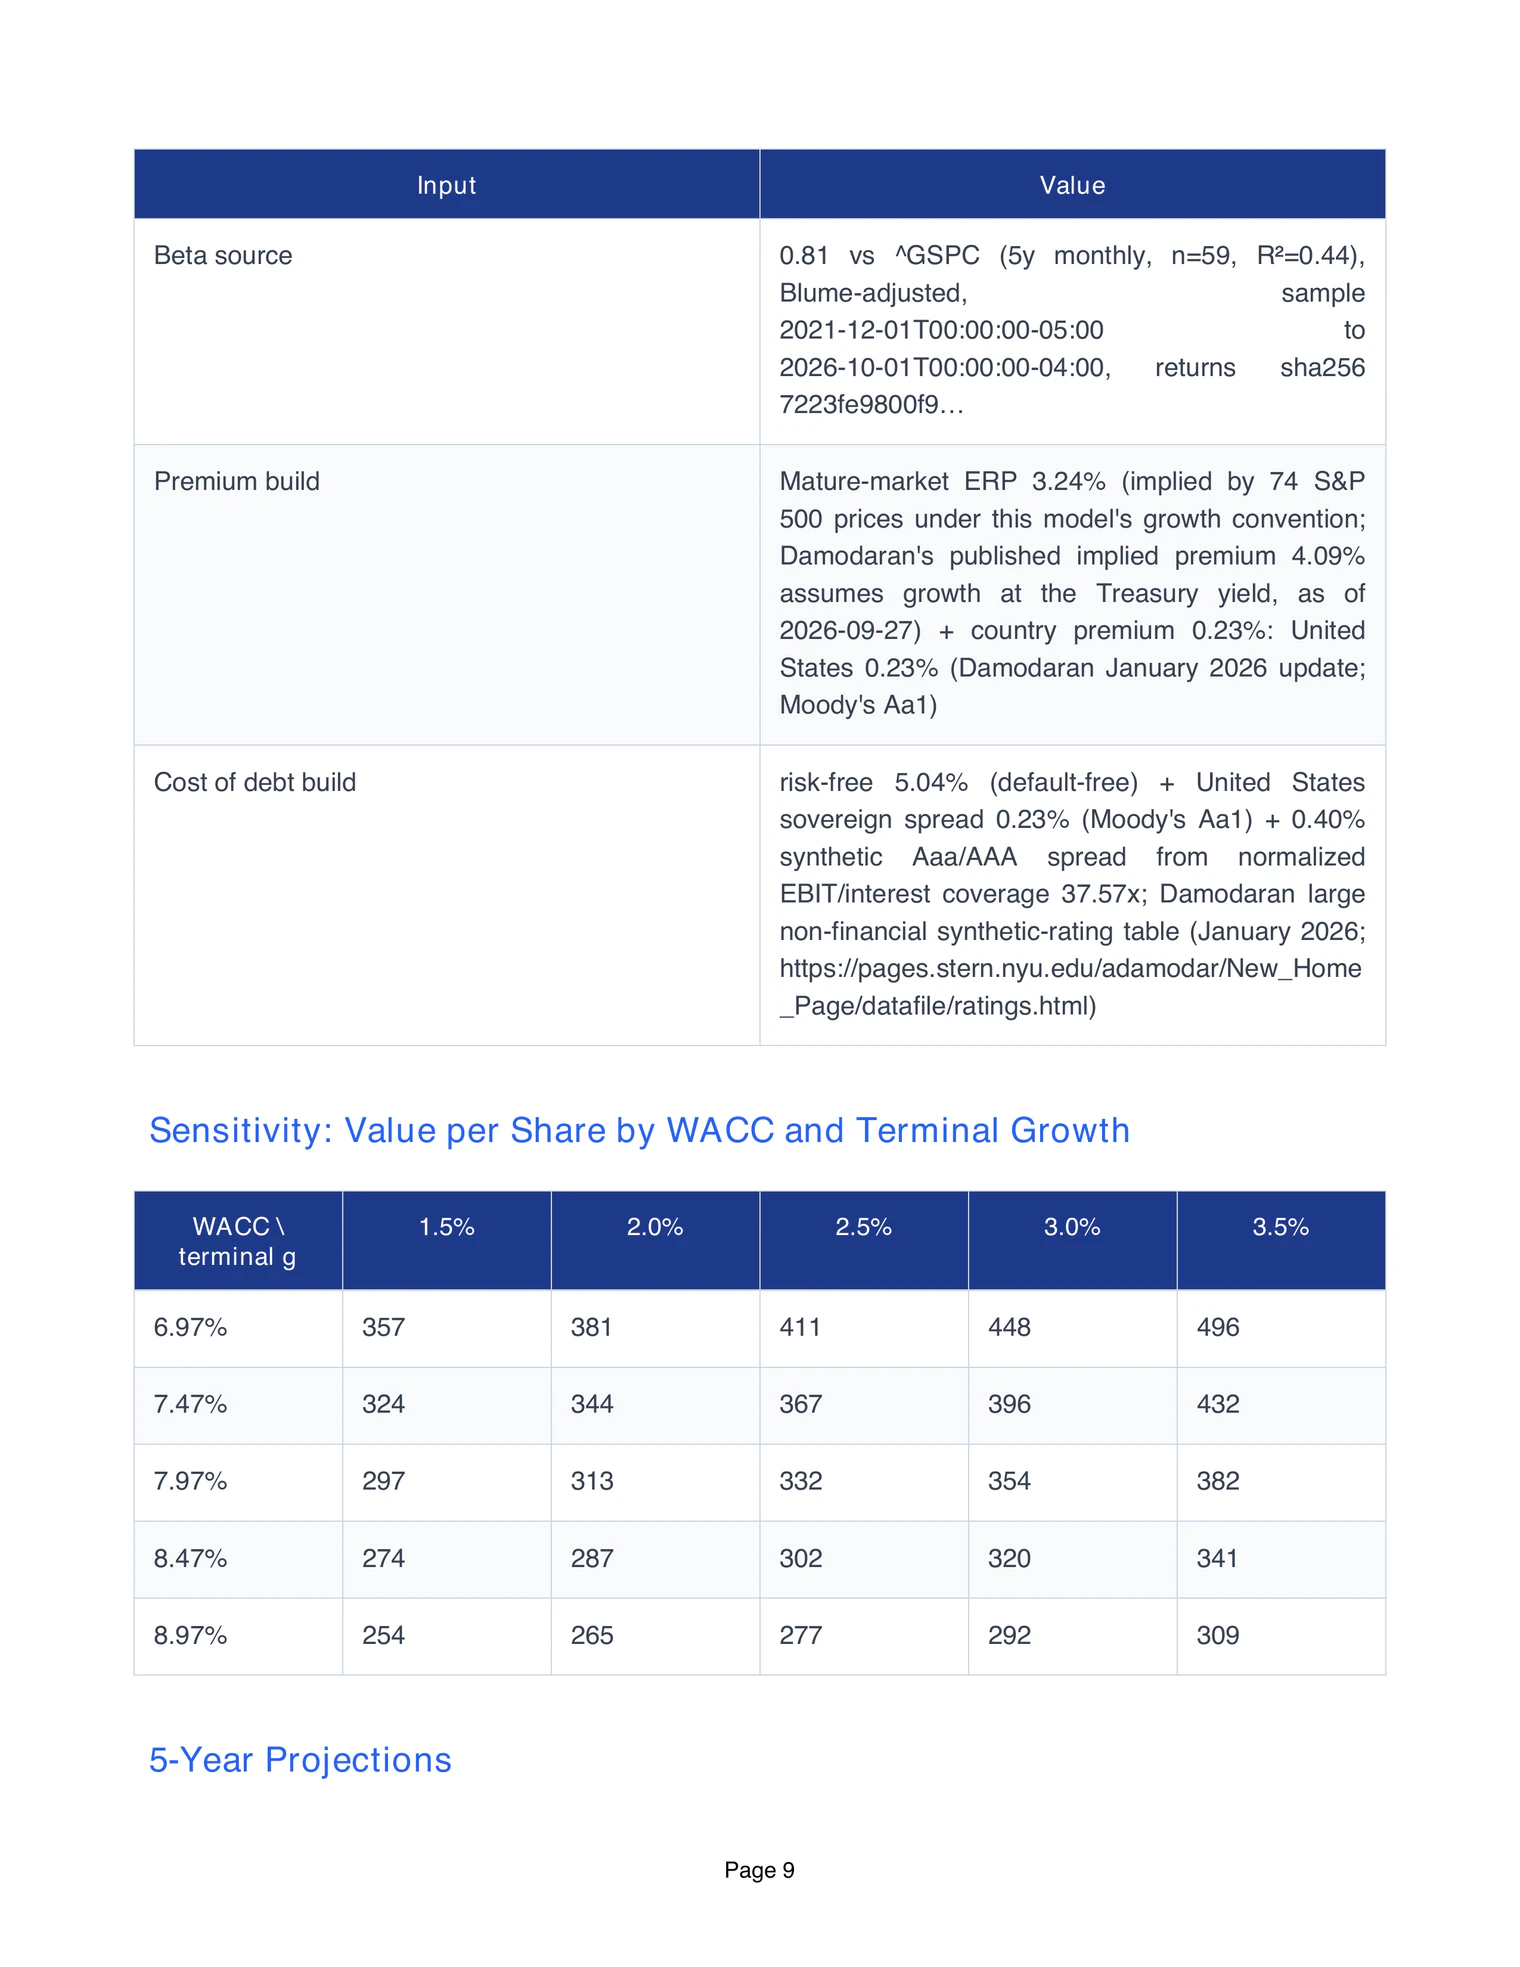
The cost of capital, built from published data
- Risk-free rate
- 4.86%
- US 10-year Treasury 5.10% (Yahoo, 16 Oct 2026), less the 0.23% US sovereign default spread (Moody's Aa1, Damodaran, Jan 2026)
- Equity risk premium
- 3.47%
- Mature-market premium 3.24%, implied by 74 S&P 500 prices, plus the 0.23% US country premium (Damodaran, Jan 2026)
- Levered beta
- 0.87
- 0.81 against the S&P 500 over 59 monthly returns, Dec 2021 to Oct 2026, Blume-adjusted
- Cost of equity
- 7.89%
- = risk-free + beta × premium
- Pre-tax cost of debt
- 5.50%
- Risk-free, plus the 0.23% sovereign spread, plus 0.40% for a synthetic AAA rating at 37.57x interest cover (Damodaran's rating table)
- Tax rate
- 17.27%
- Normalized cash tax rate, the same one used in the cash flows
- Equity weight
- 96.94%
- Market capitalisation over market capitalisation plus debt
- WACC
- 7.78%
- = equity cost × equity weight + after-tax debt cost × debt weight
What would change the answer.
The two assumptions a valuation leans on most, moved one step at a time.
| Cost of capital | Terminal growth | ||||
|---|---|---|---|---|---|
| 1.5% | 2.0% | 2.5% | 3.0% | 3.5% | |
| 6.78% | $370 | $396 | $429 | $471 | $525 |
| 7.28% | $335 | $357 | $382 | $414 | $453 |
| 7.78% | $307 | $324 | $344 | $368 | $398 |
| 8.28% | $282 | $296 | $312 | $332 | $355 |
| 8.78% | $261 | $272 | $286 | $301 | $320 |
The outlined cell is the model’s own case. Shaded cells are above the $402.61 price: 5 of the 25.
What the price and the analysts imply
| To arrive at | Cost of capital | or terminal growth |
|---|---|---|
| The model | 7.78% | 2.50% |
| The price, $402.61 | 7.05% | 3.56% |
| The analysts' mean target, $422.77 | 6.93% | 3.73% |
Each figure solves one assumption while the model’s cash flows and the other assumption stay fixed. A diagnostic, not a valuation.
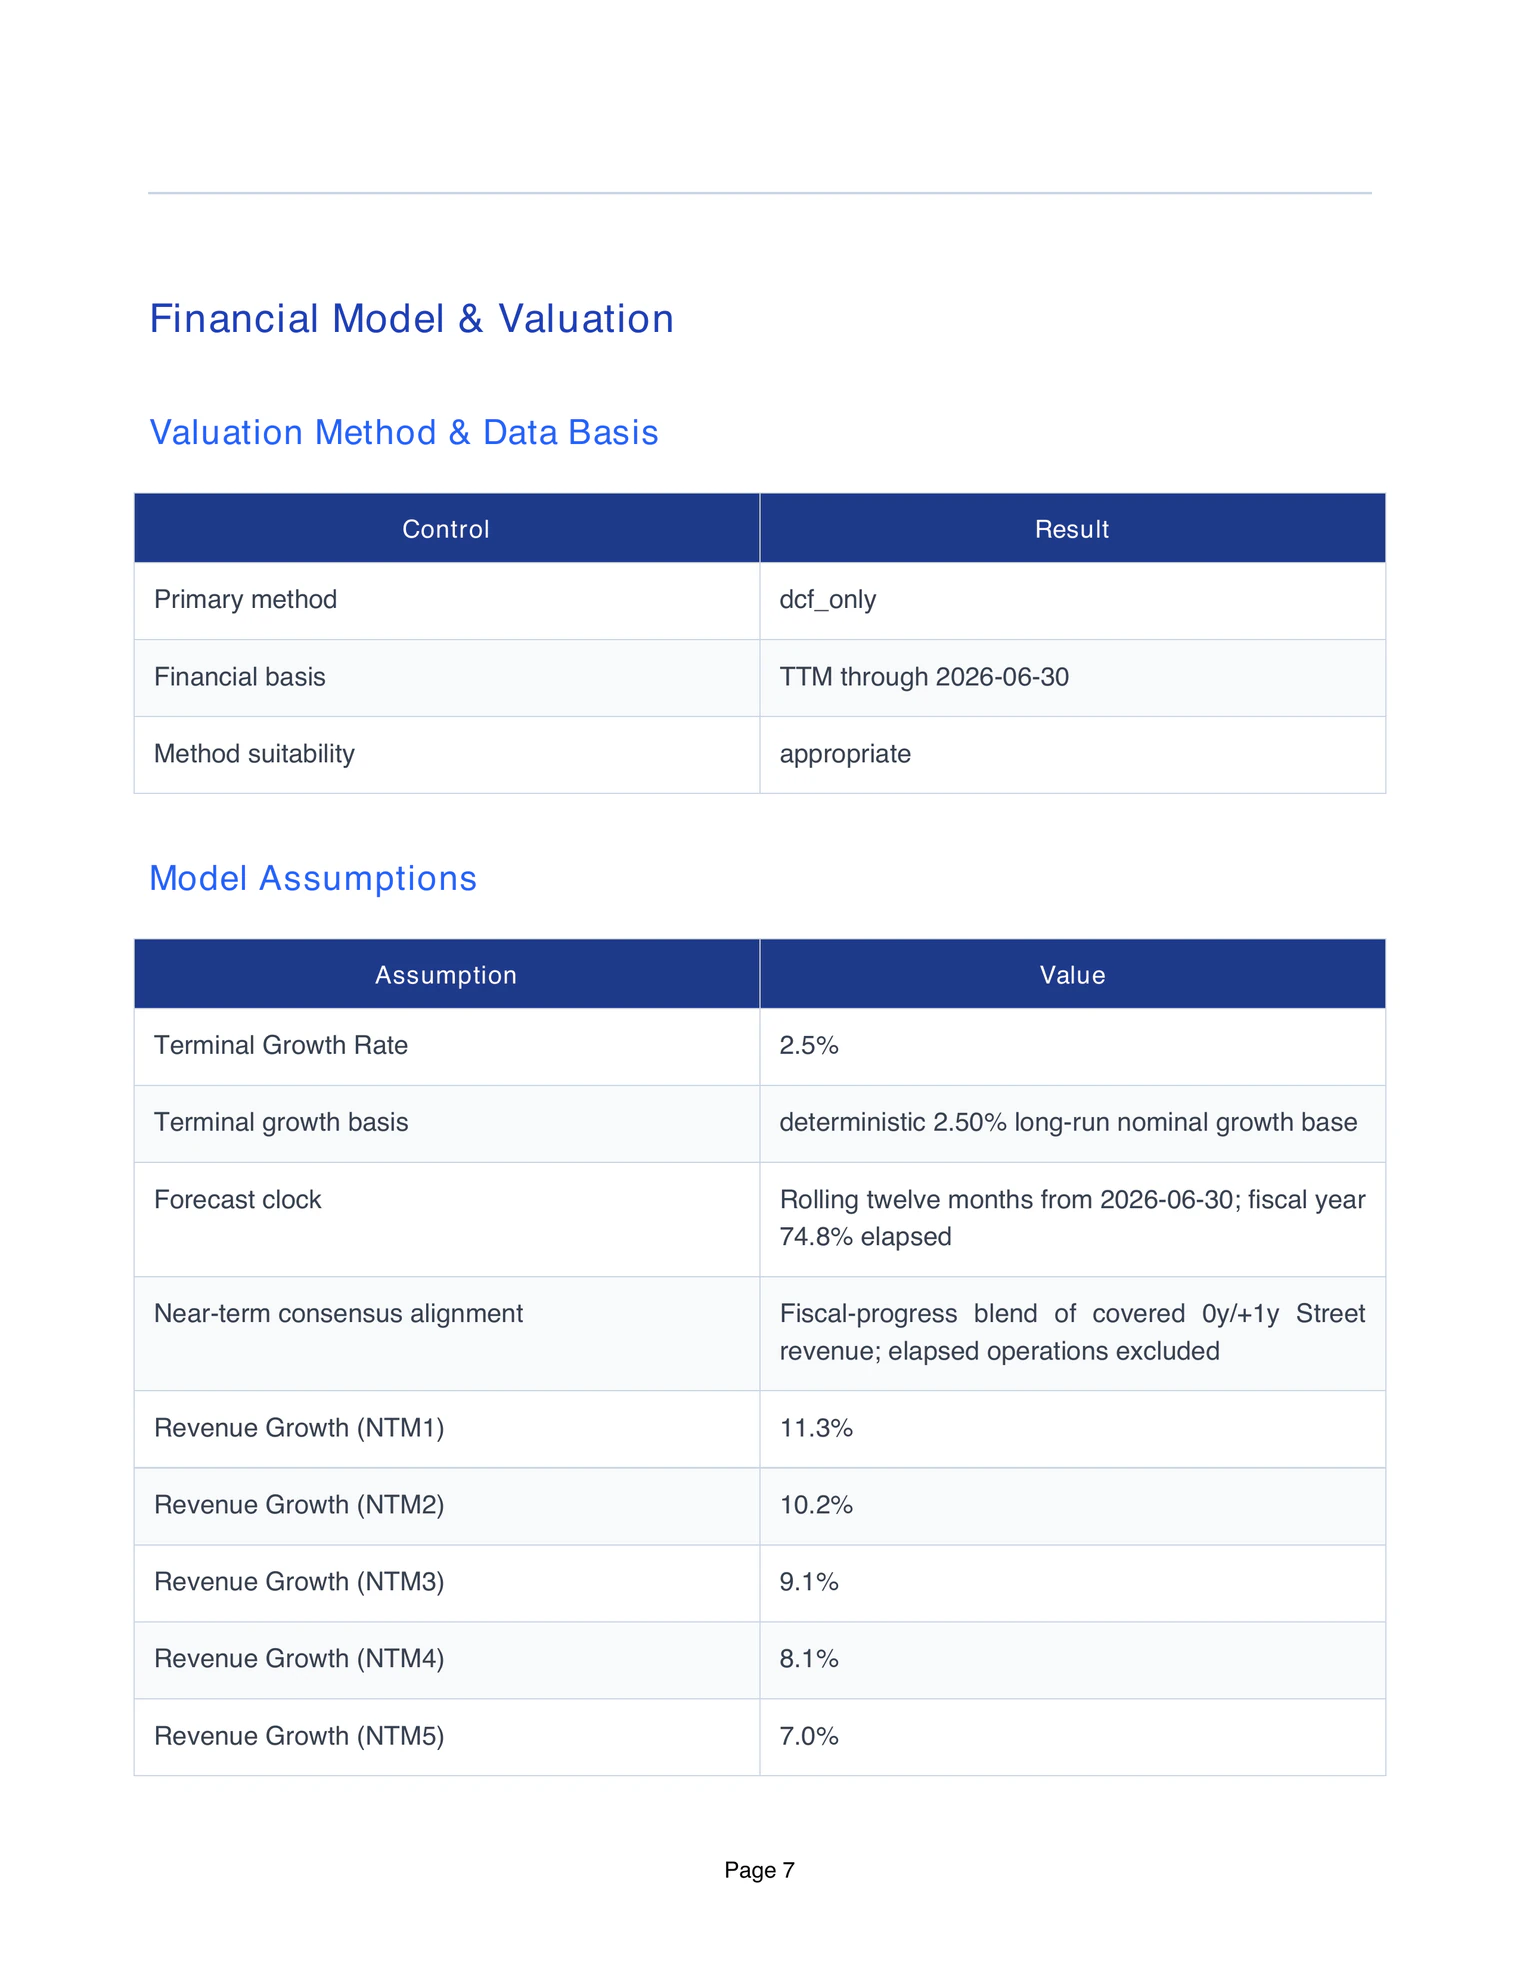
The forecast behind it.
Four reported years, then the first five of the ten the model projects.
| Year | Revenue | Growth | Free cash flow |
|---|---|---|---|
| FY2022 | $29.31B | $17.88B | |
| FY2023 | $32.65B | 11.4% | $19.70B |
| FY2024 | $35.93B | 10.0% | $18.69B |
| FY2025 | $40.00B | 11.3% | $21.58B |
| Year 1Forecast | $49.53B | 11.3% | $23.98B |
| Year 2 | $54.56B | 10.2% | $26.87B |
| Year 3 | $59.53B | 9.1% | $30.21B |
| Year 4 | $64.31B | 8.0% | $33.60B |
| Year 5 | $68.81B | 7.0% | $36.98B |
The reported years end 30 September. Forecast years run from 30 Jun 2026, so Year 1 grows from revenue over the twelve months to that date, $44.49B in the workbook, not from FY2025. The first forecast year matches analysts' revenue estimates (35 analysts) by design, which the report says is not independent validation.
What the news adds.
VYNN read 17 dated articles from the 90 days before the run, the newest from 2 Oct 2026, and classed the tone as neutral. The price target is the model’s fair value; the news is the evidence beside it.
Catalysts
Visa Foundation's $2 million small-business grant program may indirectly support the small-business ecosystem and digital adoption, but its direct financial significance to Visa appears limited.
A live Lloyds-Visa pilot demonstrated stablecoin settlement of cross-border obligations in under an hour, including outside banking hours.
Visa is part of a large consortium launching OUSD, a dollar-pegged stablecoin intended for enterprise and internet-native financial services.
Risks
The proposed European digital euro could create a publicly backed alternative to card payments and intensify pressure on Visa's European transaction volumes and fees.
OUSD faces entrenched stablecoin competitors and uncertain adoption, which could limit the value of Visa's participation.
European bank-backed Wero and policy efforts to reduce reliance on U.S. card networks could challenge Visa's European position over time.
India's UPI-led payment ecosystem limits the addressable opportunity for card-based payments, including Visa cards used through Apple Pay.
AI-accelerated cyberattacks raise the risk of payment-network compromise, service disruption, and damage to customer trust.
Each item is VYNN’s summary of dated articles, with the sources and quotations listed in the report’s appendix.
What VYNN checked before it published.
The value cleared the publication checks
The workbook's status reads Publishable: the deterministic valuation publication checks passed.
Confidence is stated as low, and why
The two methods share one cash-flow forecast, one discount rate and the same terminal economics, and no independent peer-multiple method was available. The report calls the result a scenario range, not an independently triangulated value.
Analysts' targets stay outside the value
Price targets and ratings are shown as a benchmark and are never averaged into the fair value. Analysts' revenue estimates do anchor the first forecast year (35 analysts), and the report says so.
Prose that could not be supported was left out
One claim in the written recommendation did not pass the claim-to-evidence check after rewrite attempts. The report omits that prose and prints the source headlines instead.
The files from this run.
Check any step, or change an assumption yourself.
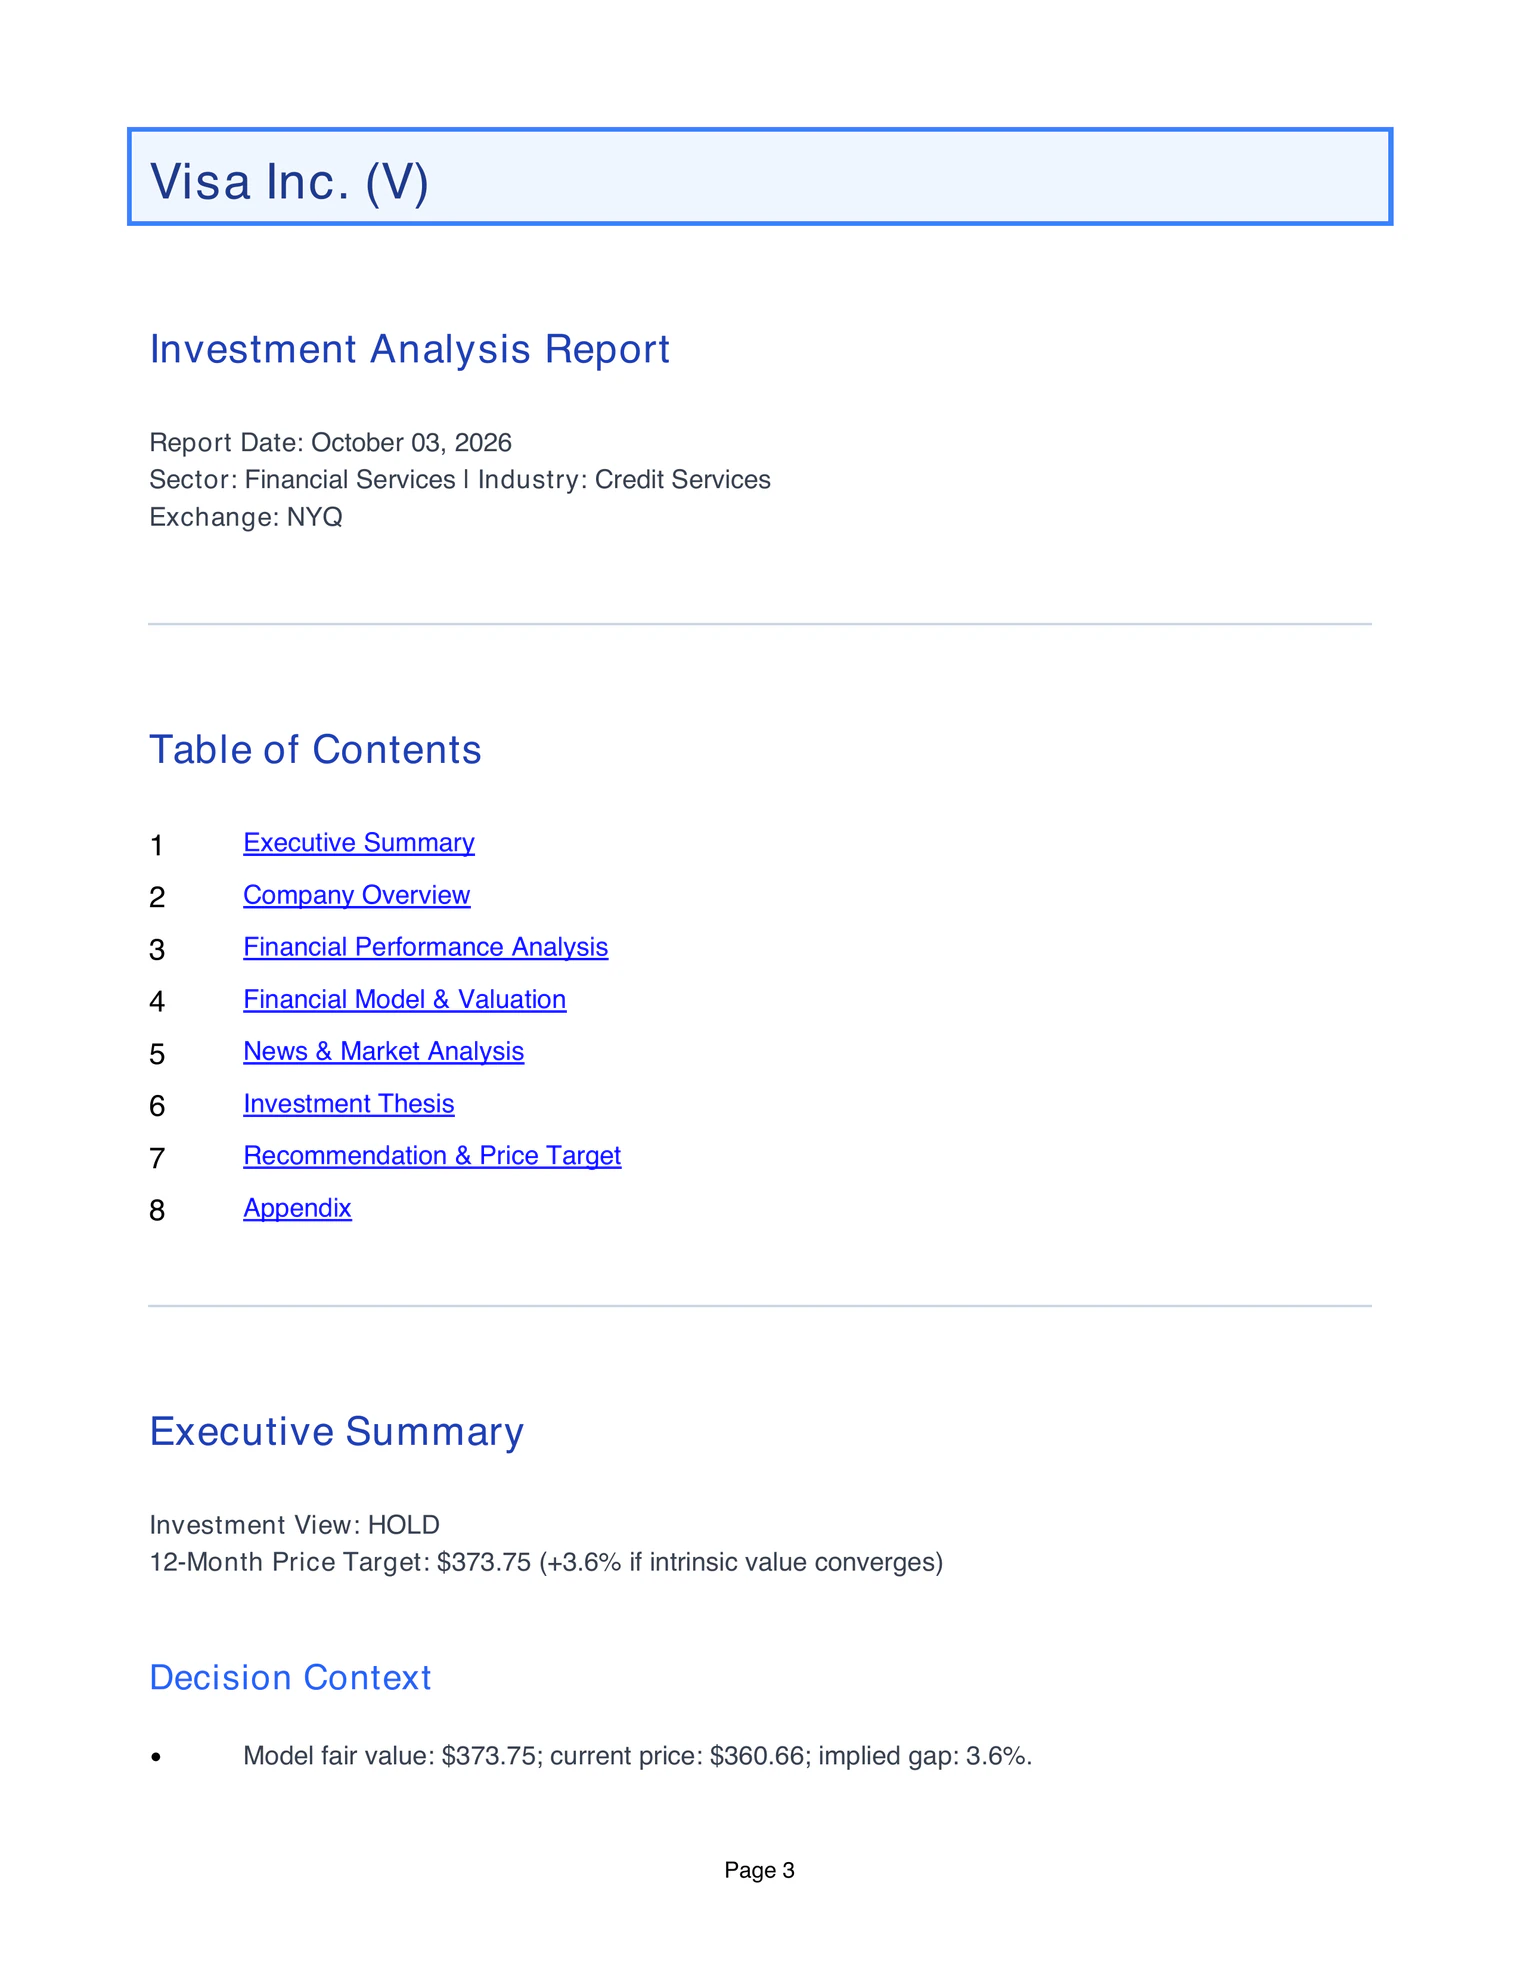
- The research reportPDF, 33 pages
- The financial modelExcel, 10 tabs with live formulas
- Engine valuation-2026-09-27.1. Generated 18 Oct 2026, 08:21 UTC.